For real estate agents

Your listing can answer the question buyers actually have.

Not the price — they can see the price. What would it cost me every month? The answer comes from the lender you already work with, priced live, and it keeps itself current without anyone touching it.

Add a QR code to the flyer you already make · free to you · nothing to sign up for

What the buyer gets

On your listing
From your lender, not from us

Your lender’s own rates, priced live

Not a national average and not our number — what your lender would actually quote today.

Nothing asked of them first

No credit check, no contact form

They explore anonymously instead of bouncing off a lead-capture wall.

When the number feels out of reach

Four routes to the payment they want

Buyer sees how to buy the home with their desired payment.

Already on listings across the country

Provided by originators at these lenders and hundreds of independent shops. Ask yours.
1,800+

Originators

$0

Cost to you

What changes

Homebuyers stall on the payment, not the price

A homebuyer loves the house, then runs the math on whatever generic calculator comes up first — using rates no lender is actually quoting. The payment looks impossible, so they move on. You never hear from them and never find out why.

On the listing

The answer is there when your loan officer isn’t

Sunday evening browsing, an open house you’re running alone, a buyer who won’t ask. The mortgage flyer answers in all three — with your lender’s live pricing, so the number is one they will actually stand behind on Monday.

  • Instantly show the value of the seller credit to buy down the rate
  • Taxes, insurance, and HOA included — the real numbers
  • DPA and buydown options your lender actually offers
In the conversation

Something concrete to bring your seller

When a buyer says the payment doesn’t work, you usually have one lever: price. This gives you three more, each of them priced.

  • “A seller-paid buydown gets them there” is a specific proposal
  • Turns a lost showing into a structured negotiation
  • Makes a price reduction the last option rather than the first
What the buyer sees

A financing flyer, not another ad for the house

The property details are yours and stay yours. This carries the financing side only — the payment, the options, and the loan officer’s contact info.

  • Your listing, your photos, your marketing — untouched
  • Or skip the separate flyer entirely and add a QR code to your own flyer
  • Every figure priced from your chosen lender’s rates, using live pricing
  • Share it, post it, or leave it at the open house

All figures are estimates, subject to change and full qualification, provided by the originating lender.
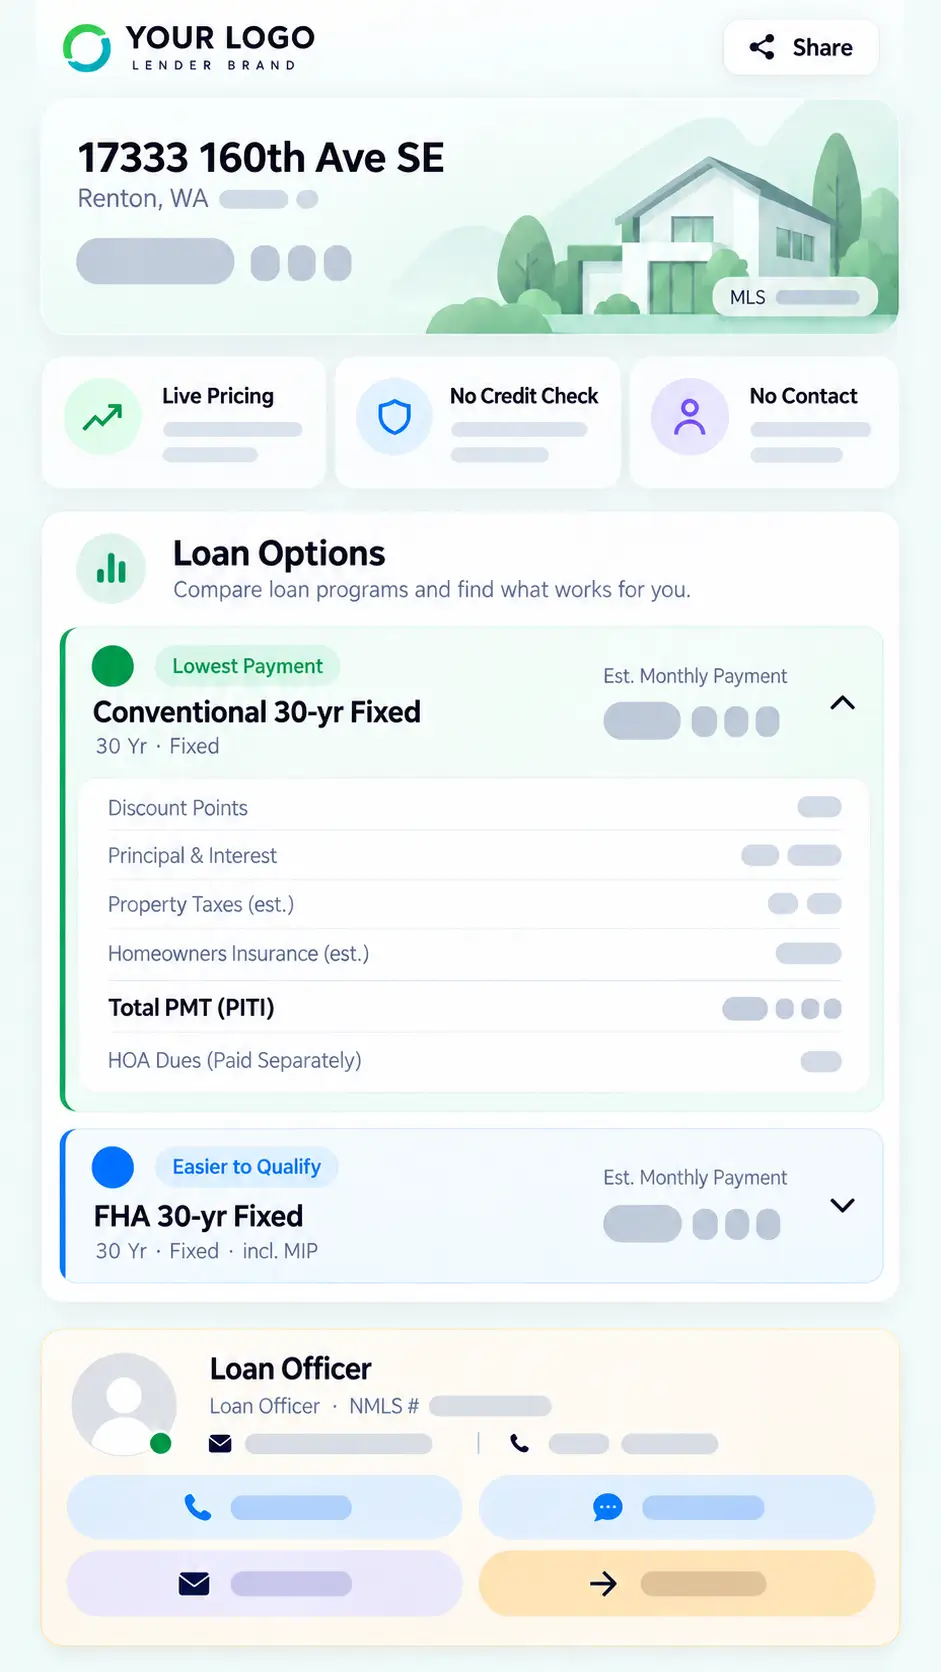
Loan options page showing a property summary, conventional and FHA mortgage options with estimated monthly payments, and loan officer contact information.
Actual Product — Rates and payments obscured for this page
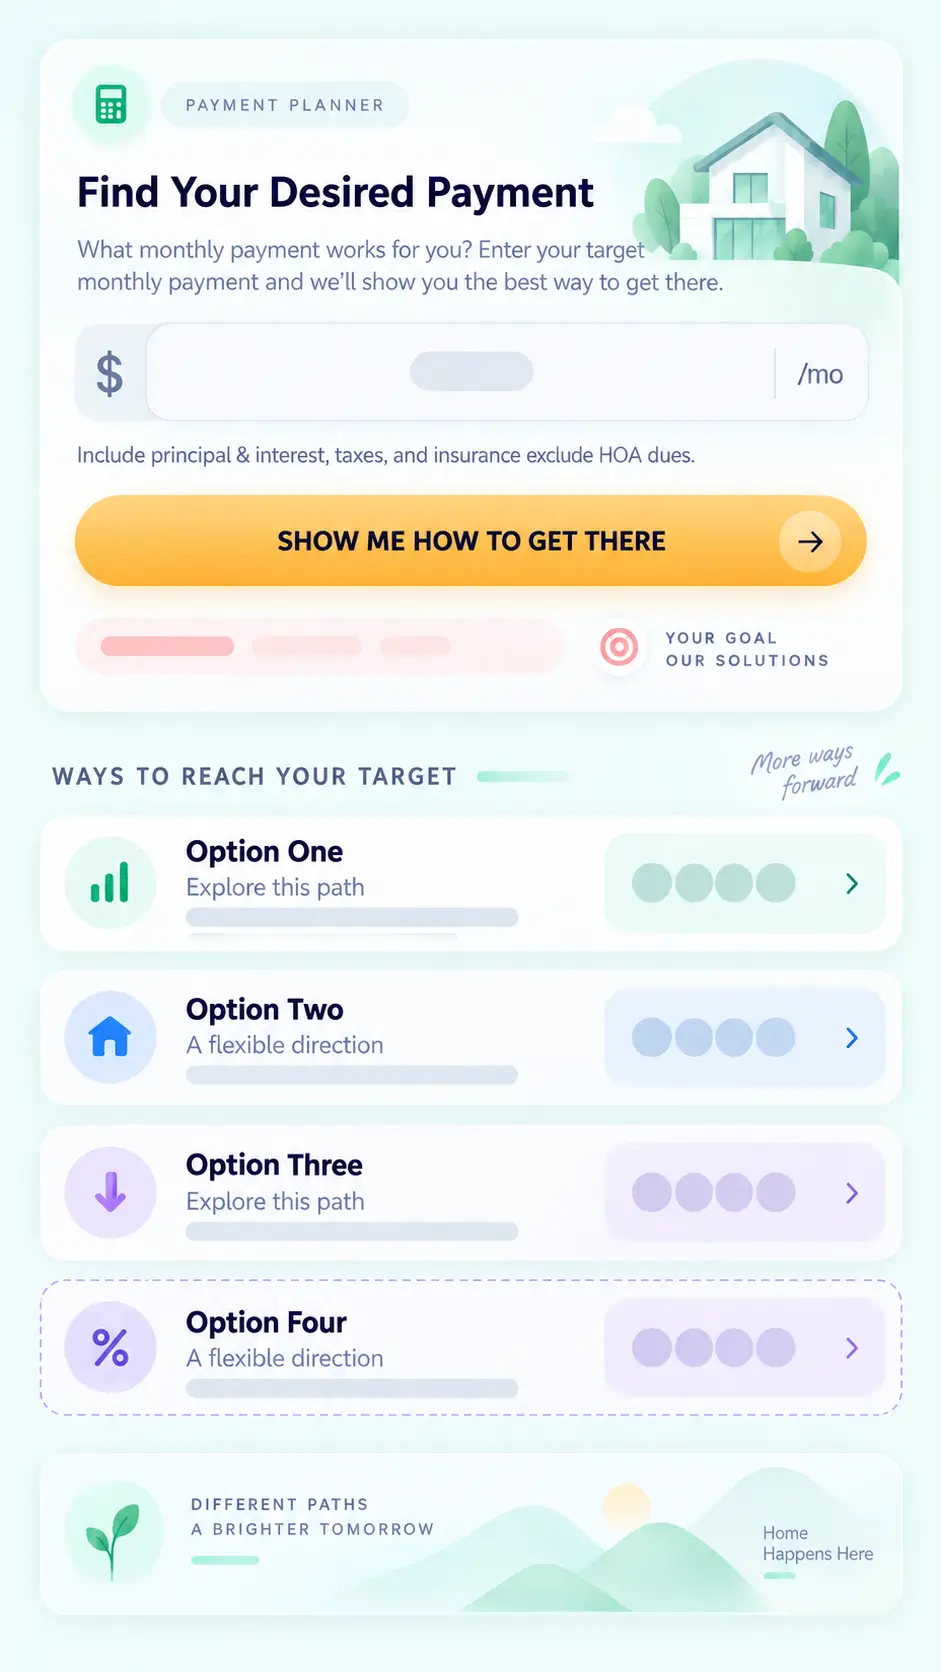
Payment planner showing a target monthly mortgage payment and ways to reach it, including a rate buydown, lower home price, higher down payment, and temporary buydown.
Actual Product — Rates and payments obscured
The part agents ask for by name

“Show me how to get there”

A homebuyer types the payment that works for them. Four routes come back, each one priced.

  • A buyer who was about to walk gets a path instead
  • You learn exactly what the gap is, in dollars
  • Seller-paid options become a negotiating position, not a guess
  • The buyer contact your lender already knowing the shape of the deal
What it asks of you

Nothing, which is the point

Your loan officer subscribes to Uplist and generates the financing flyer. You put it wherever you’d put anything else.

No cost

The lender pays for it. There is no agent tier and nothing to expense.

No account

Nothing to sign up for, install, or learn. You receive a flyer or a QR code.

No compliance change

It carries financing information only, so your own marketing obligations don’t move.

No exclusivity

It’s your listing. Work with whichever lenders you already work with.

Getting it on your listings

Keep your flyer. Add a QR code.

Uplist is provided by loan officers to the agents they work with, so it starts with a conversation you were probably having anyway. If yours already has it, you can be using it this week.

Keep your flyer. Add a code.

Add your lender’s QR code to the mortgage flyer you already make

Your design, your photos, your branding — unchanged. Your loan officer sends you a code and you drop it on. A buyer scans it and lands on live payment options priced from your lender.

  • The code carries no rate and no payment, so your flyer stays a plain real-estate flyer never needs updating
  • Works on print, window cards, sign riders, and open-house handouts
  • Disclosures live on the page it opens, not on your material
Or let them make it

Ask for the mortgage financing flyer

If you’d rather not add anything to your own materials, your loan officer can generate a separate financing flyer for the property and send it over. Share it, post it, or leave it at the open house.

  • Nothing for you to design or produce
  • Financing information only — it doesn’t compete with your listing marketing
  • Ready in a few minute once they have the address. No rates on the flyer means no reprinting every week
If your lender doesn’t have it yet

Send us their name and we’ll show them how it works. If you don’t have a preferred lender, we can make an introduction.

Whose numbers these are

Uplist is not a rate source. Every payment a buyer sees is priced from the pricing engine of the loan officer who generated that flyer — the one you chose to work with. When their pricing moves, the flyer moves with it. Nothing on it is ours.

Worth saying plainly

Uplist does not rank lenders, or maintain a directory. Which lender you work with is your decision and your client’s.

Questions agents ask

Before you ask your lender

Yes, and it’s the option most agents prefer. Your loan officer sends you a code, you place it on the flyer you already produce, and your design and branding stay exactly as they are. The code carries no rate and no payment — those appear on the page it opens, along with the lender’s disclosures and NMLS.

No. The loan officer subscribes to Uplist and provides the financing flyer. There is no agent subscription, no per-listing fee, and nothing for you to expense.

The flyers carry financing information only. They do not promote the property and they carry no agent branding, which is the distinction between a financing tool and co-marketing. The structure has been reviewed by counsel. As always, check with your own broker on your brokerage’s policies.

Your loan officer’s. Uplist is not a rate source and does not set pricing — every payment a buyer sees is priced live from the pricing engine of the originator who generated that flyer, through connections to Optimal Blue, Polly, and LoanSifter. When their pricing changes during the day, the flyer changes with it.

Not unless you want one. If you add a code to your own marketing, the code carries no rate and no payment — those live on the page it opens, along with the lender’s disclosures and NMLS. Your flyer stays a plain real-estate flyer.

No. Buyers see live payment options with no credit pull, no Social Security number, and no contact form. They explore anonymously and reach out when they choose to, which means fewer of them bounce off your listing.

Yes. Each flyer is tied to the originator who generated it, so if you work with several lenders you can use flyers from any of them. Uplist has no exclusivity requirement and no say in who you work with.

Send us their name and we’ll reach out to show them how it works. We do not recommend lenders, rank them, or introduce agents to lenders — we contact the person you already work with.

Next step

Tell us who your lender is

Your listings, priced by the lender you already trust. We’ll show them how it works — and if they already have it, we’ll tell you that instead so you can start this week.

Selling new construction?

Uplist is a technology provider. Uplist is not a lender or mortgage broker, does not originate loans, and does not make credit decisions. Any payment or rate figures shown through Uplist products are estimates provided by the originating lender, are subject to change, and are not a commitment to lend or a guarantee of approval or of rate availability. Pricing shown on this page is subject to change. Equal Housing Opportunity.

Go to Top