For home builders

Let homebuyers build the payment they want.

Live pricing from your preferred lender, with your seller credits and buydowns already in the math. A homebuyer can also name the payment that works for them and sees exactly what it takes to get there — on every home.

No builder subscription · your lender provides it

At the model home

Live
Before you reach for a concession

Four routes to their payment

Buyer sees how to buy the home with their desired payment.

From your lender, not from us

Your preferred lender’s own pricing

Priced live and refreshed through the day — a generic printed rate that goes stale.

Nothing asked of them first

No credit check, no contact form

They explore anonymously instead of bouncing off a lead-capture wall.

Running with lenders who serve builders

Deployed by originators at national platforms and independent shops, in communities and on scattered-site inventory.
1,800+

Originators

3

Pricing engines

What changes

Spend the incentive where it actually moves someone

Home builder financing tools should do more than advertise a rate. Uplist helps builders understand the payment a homebuyer needs, compare financing options, and determine whether a seller incentive is necessary before offering one.

A community-wide buydown is a blunt instrument. It comes off every home, including the ones that would have sold anyway, and it still never reaches the buyer who quietly decided the payment was out of reach and left without saying so.

Uplist mortgage intelligence platform provides mortgage tools for home builders that combine live lender pricing, buyer payment options, seller buydowns, and financing scenarios to help move more buyers forward.

On the sales floor

Find out what the gap is before you close it

When a homebuyer says the payment doesn’t work, the number they need is usually knowable. Uplist puts it on the screen along with what it would take to get there, so the conversation starts from actual numbers, rather than a guess.

  • See the exact dollar gap between their number and the plan
  • Compare a seller-paid buydown against other routes, side by side
  • Down payment assistance options your lender offers, applied automatically
On every home

Answers that don’t wait for a loan officer

Potential buyers can get a real payment options without waiting for someone to be free.

  • QR codes on flyers, signage, or anywhere else
  • Live payment scenarios per plan, per lot, per quick move-in
  • Display live pricing on your website for each house
What the buyer sees

Your preferred lender’s numbers, on the homebuyer’s phone

Uplist is not a rate source. Every payment is priced from the pricing engine of the lender you already work with, always live.

  • Total payment including taxes, insurance, and HOA
  • Conventional, FHA, VA, and other scenarios ranked side by side
  • Loan-level price adjustments already applied
  • Instantly show seller credit

All figures are estimates, subject to change and full qualification, provided by the originating lender. The page says so in the buyer’s view.
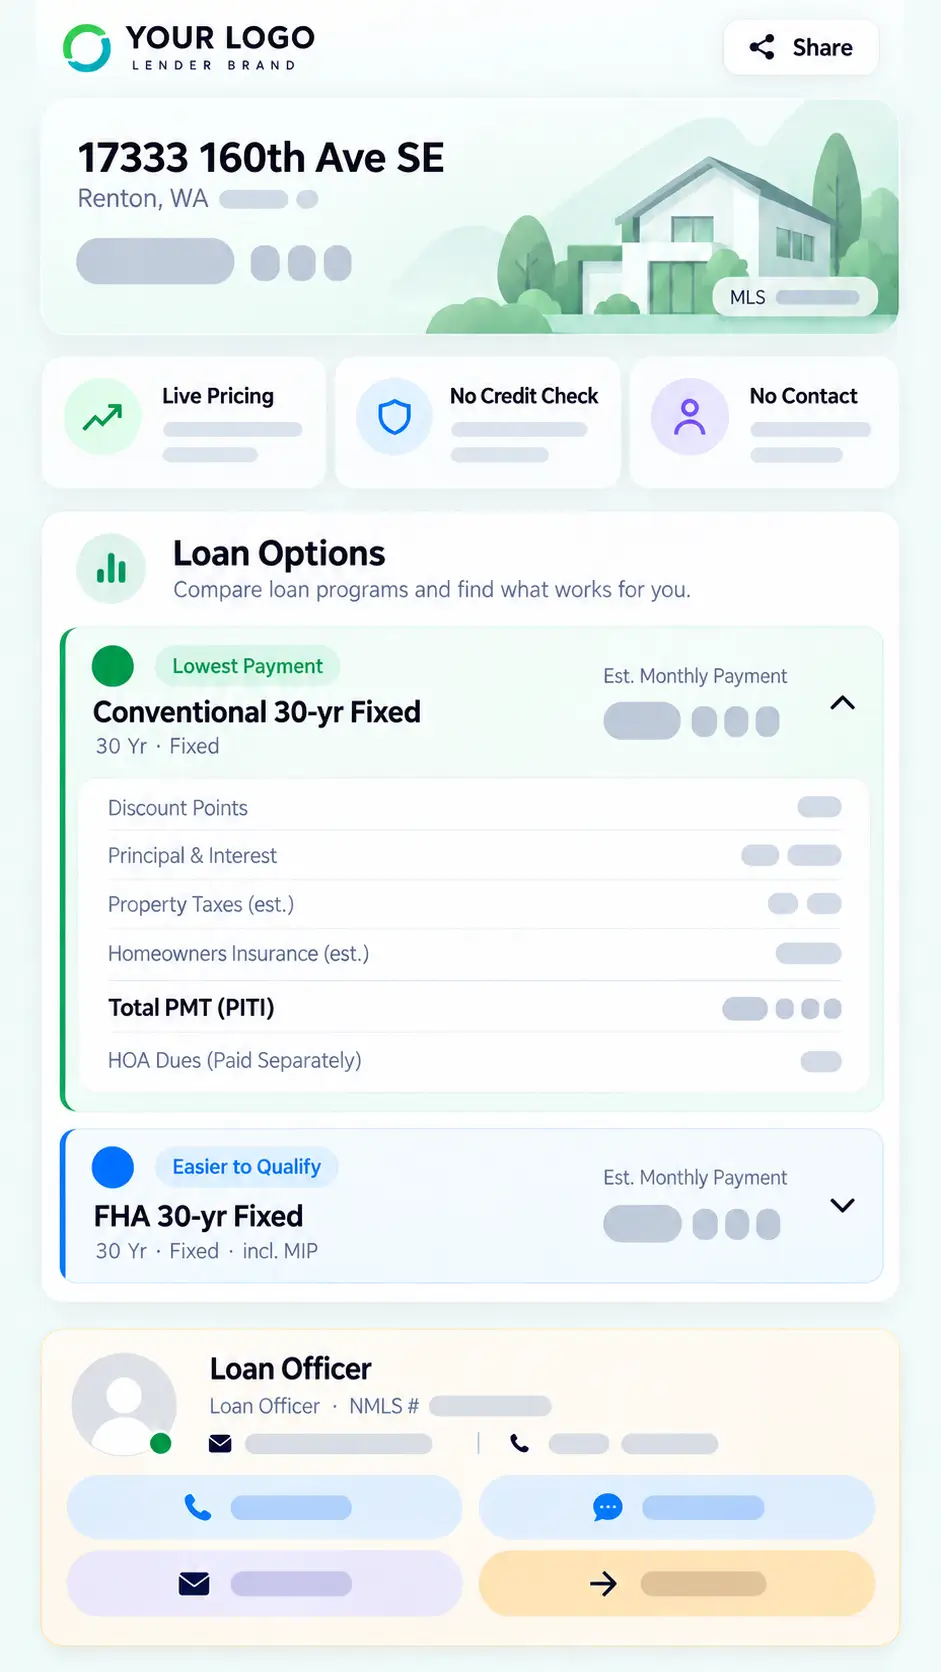
Loan options page showing a property summary, conventional and FHA mortgage options with estimated monthly payments, and loan officer contact information.
Actual Product — Rates and payments obscured for this page
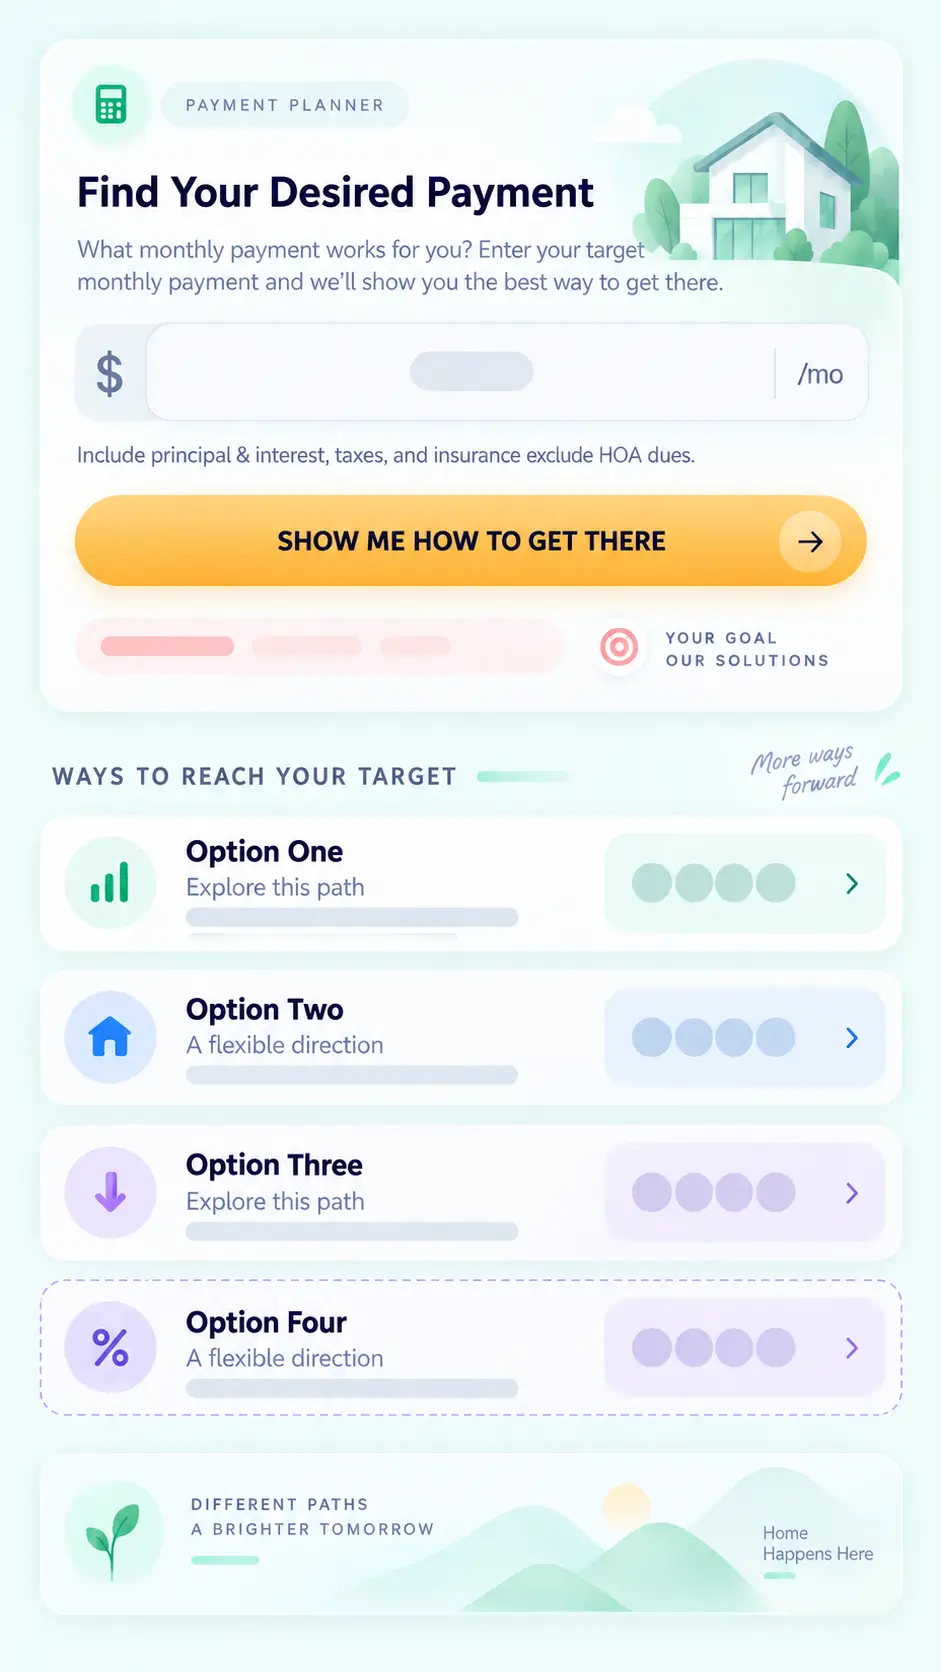
Payment planner showing a target monthly mortgage payment and ways to reach it, including a rate buydown, lower home price, higher down payment, and temporary buydown.
Actual Product — Rates and payments obscured
The one that matters most here

“Show me how to get there”

A homebuyer types the payment that works for them. Four routes come back, each priced

  • Shows whether the gap needs an incentive at all, or just a different structure
  • Sizes the concession precisely instead of applying one across the community
  • Surfaces options that may cost you nothing
  • Turns a lost walk-through into a specific, priced proposal

Sales uses it live in the model. It can be the difference between “we can probably do something” and a number that works for the buyer.

Where it lives

One QR code, everywhere a buyer looks

Your preferred lender generates the QR codes. You put them on the materials you already print, with nothing to redesign.

On what you already produce

A QR code you drop onto existing materials

Your brand, your layouts, unchanged. The code carries no rate and no payment, so nothing about your printed material changes.

  • Model home displays
  • Spec sheets and brochures
  • Sign riders, window cards, and lot signage
  • Community website and plan pages
Or a ready-made sheet

Financing flyers per plan or per home

Your lender can generate a separate financing sheet for individual properties. Financing information only — it doesn’t compete with your own marketing.

  • Nothing for your marketing team to design
  • Refreshes on its own as pricing moves
  • Useful for realtor outreach
Questions builders ask

Before you bring it to your lender

Your preferred lender’s. Uplist is not a rate source and does not set pricing — every payment is priced live from that lender’s own pricing engine through connections to Optimal Blue, Polly, and LoanSifter. When their pricing changes during the day, the buyer’s view changes with it.

No. Most builders add a QR code to materials they already print. The code carries no rate and no payment, so your layouts, brand, and disclosures stay as they are. Your lender can also generate a separate financing sheet per plan if you’d rather keep the two apart entirely.

Yes, where your lender offers it. Assistance options, seller credits, and buydown structures are applied inside the payment scenarios a buyer sees, so the number reflects what is actually available to them rather than a generic estimate. Program availability and eligibility are determined by the lender.

No, it informs it. Seeing the exact gap between a buyer’s target payment and the plan lets you size a concession to the buyer in front of you rather than applying one across the community — and sometimes it shows the gap can be closed with a structure that costs you nothing.

Uplist is licensed by the lender, not the builder. Your preferred lender subscribes and provides the codes and flyers. There is no builder subscription and no per-home fee.

No. Buyers see live payment options with no credit pull, no Social Security number, and no contact form. They explore anonymously and reach out when they choose to, which means fewer of them leave the community site without ever identifying themselves.

Next step

Bring it to your preferred lender

Tell us who they are and we’ll show them how it works. If they already have it, you could be running QR codes in your community this month.

Working with resale listings too?

Uplist is a technology provider. Uplist is not a lender or mortgage broker, does not originate loans, and does not make credit decisions. Any payment or rate figures shown through Uplist products are estimates provided by the originating lender, are subject to change, and are not a commitment to lend or a guarantee of approval or of rate availability. Pricing shown on this page is subject to change. Equal Housing Opportunity.

Go to Top