
Recapture · Homeowner Intelligence
Every loan you closed, reviewed continuously. Including the ones to leave alone.
Uplist Recapture™ is mortgage refinance monitoring software that watches your closed portfolio against the market and hands originators a decision with the analysis finished — priced on your own rates, adjustments included.
Already running Recapture
Independent mortgage banks, depositories, and credit unions — from single branches to national platforms. Designed and built by top-producing originators.
700K+
Loans watched
3
Pricing engines
What Recapture does
A call list your originators will actually work
Uplist Recapture™ reviews every closed mortgage loan against current pricing, does the analysis, and hands over the ones worth a conversation.
Why the list gets worked
The analysis happens before anyone is asked to call
Propensity scoring creates too many false positives. Calling a past client about an opportunity that isn’t real costs a relationship, so most originators end up calling nobody.
- Every name already checked against today’s market on your own pricing
- Loan-level price adjustments applied for accurate analysis
- The payment change and break-even clearly identified
Why the book stays covered
Retention that doesn’t depend on anyone’s discipline
Portfolio retention usually rests on individual habit, which means it lapses exactly when a producer leaves and their book goes quiet. Nobody decides that — it just stops being anyone’s job.
- Every closed loan monitored, not a scored or sampled subset
- Books can be reassigned when someone departs
- Coverage becomes an institutional fact rather than a behavior
Verified, not predicted
Every review returns a decision, not a probability
Mortgage refinance monitoring runs continuously. Three potential outcomes with clear decisions to act on.
- Two of the three say don’t call. That’s what makes the third one worth acting on
- No scores, no rankings, no percentage likelihood to translate
- A short list that’s correct beats a long one that’s inaccurate
After 90 quiet days, the borrower hears from you anyway — that their loan was reviewed. Cadence and messaging is yours to set.
What reaches the borrower
Two emails, both sent in your name
One carries a finished analysis. The other carries nothing to sell. Together they are the reason a past client still recognises your name a year later.
When there’s something real
The mortgage loan has already been priced against your current rates with adjustments applied. What reaches the borrower is the completed analysis — the payment change, the break-even, and the option the originator would have recommended anyway.
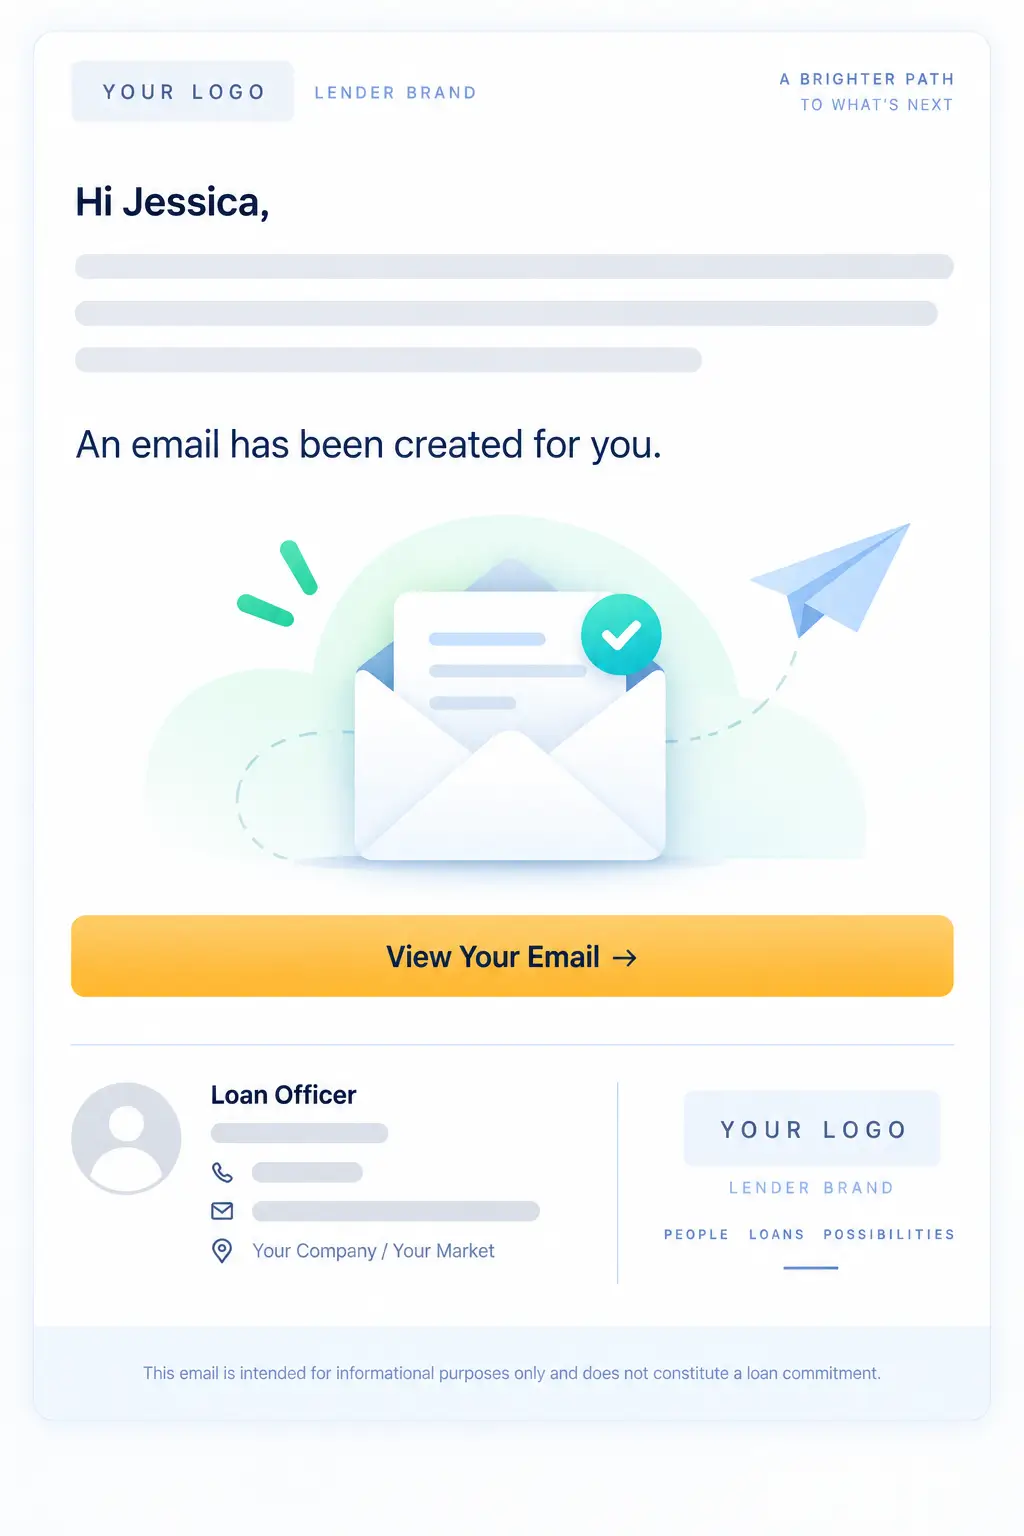
ACTUAL PRODUCT — FIGURES OBSCURED. SENT UNDER YOUR BRAND, WITH THE ORIGINATOR’S NMLS.
When there isn’t
Your borrower’s inbox is full of people selling them something. Be the one who writes to say nothing needs to change. It costs nothing to send, and it is why the next email gets opened.
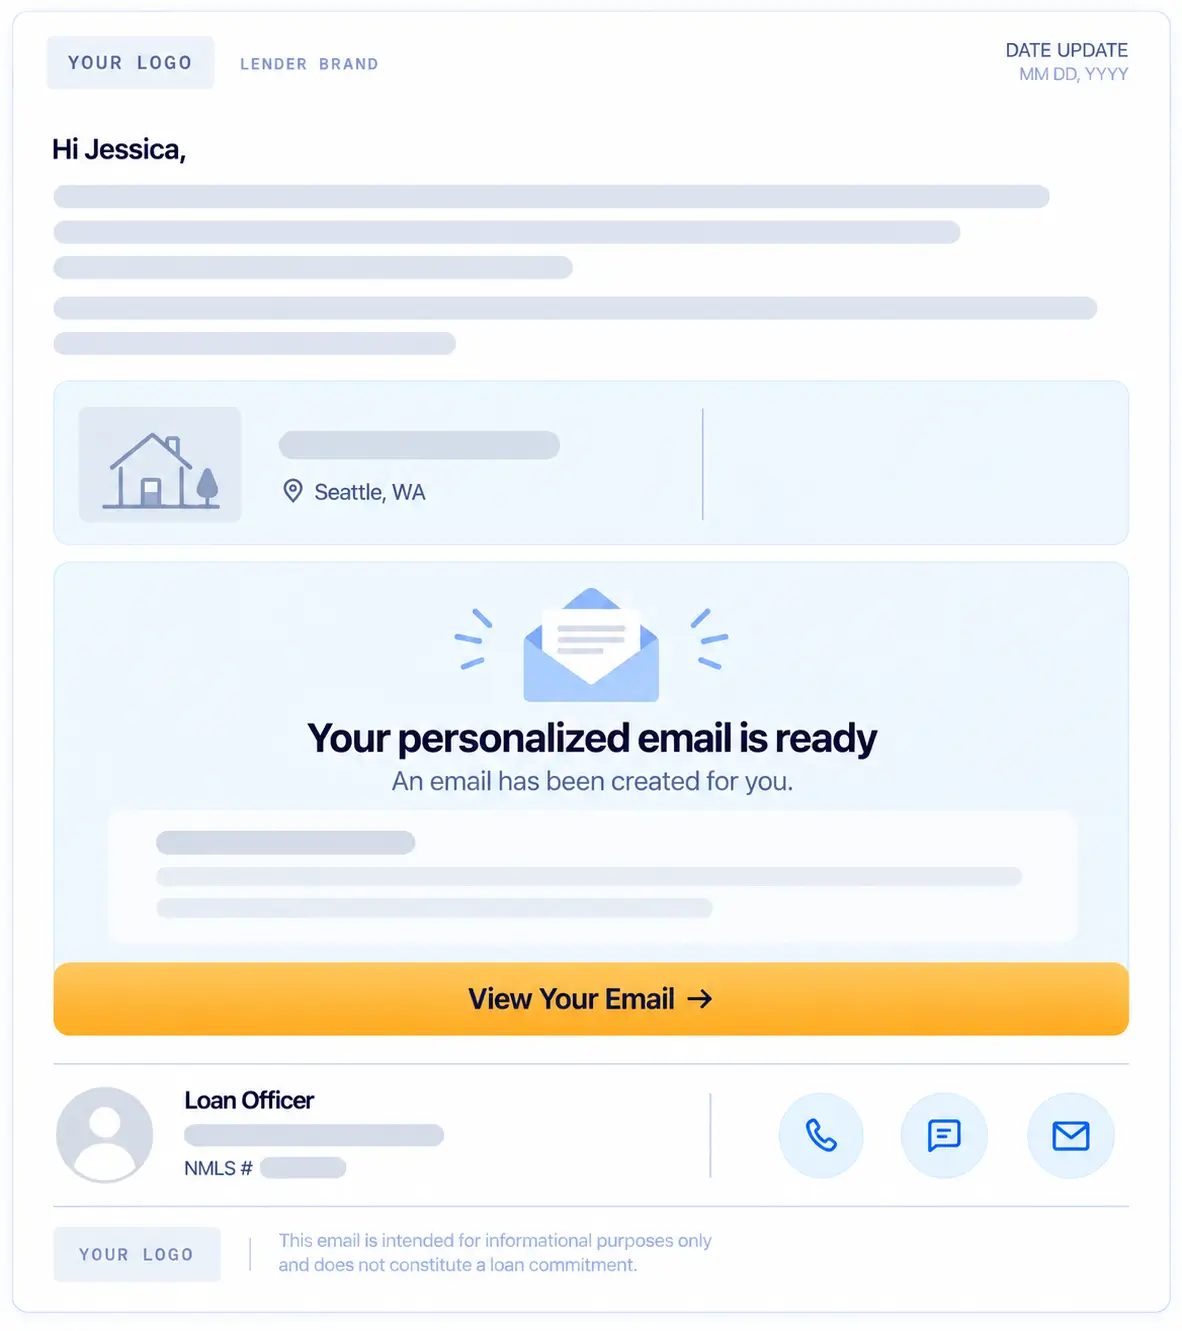
SENT AFTER 90 QUIET DAYS — CADENCE IS YOURS TO SET
Analysis before contact
Priced on your rates with adjustments applied. The work is finished before anyone is asked to call.
Trust between the deals
Borrowers learn you’re watching out for them, so the call you do make gets taken.
Your brand only
Your logo, your originator, their NMLS on every borrower email.
Your disclosure language
Configurable footer, so compliance approves once rather than every send.
Rollout
Nobody has to log in for this to work
Retention tools rarely fail because the software is bad. They fail at rollout, because they ask people with full pipelines to add a daily habit. Uplist Recapture™ asks for nothing from the mortgage loan originator, and returns something of value.


Your portfolio, your relationship
Built on loans you already own
Uplist Recapture™ works inside the book you originated or service. No purchased list, no third-party trigger feed, no dependency on a channel that’s narrowing.
Since March 2026, federal law has sharply restricted who can receive mortgage trigger leads — largely limiting them to institutions that already hold the borrower relationship. Lenders who built retention on purchased data are rebuilding. If your retention runs on your own portfolio, nothing changed.
Pricing
Cheaper than the loans it saves
Mortgage retention tooling gets evaluated as a software line item. It’s more useful to measure it against a single funded loan.
Priced per user. Against the margin on one retained loan, covering an originator’s entire book for a year is a rounding error, and a retained loan is the cheapest loan you will ever originate.
PROOF
What lenders say
Chief Lending Officer, PRMG
1,800+
Users on the platform
700K+
Loans under continuous review
80+
Lenders trust Uplist
Lenders, Banks, Brokers, Credit Unions
3
Pricing engines connected
