Homebuyer Intelligence

Give your mortgage listing flyers a brain.

Mortgage listing flyers that use your actual rates, that’s Homebuyer Intelligence. Put your live pricing on it and it answers the only question a buyer actually has — what would this cost me every month?

What the flyer does

Live
Priced at the moment they look

Live Pricing

Your rates, not a national average. Flyers never need updating.

When the buyer already has a number

Find Your Desired Payment

Users enter the payment that works for them and get up to four routes to reach it.

Adjustments applied, not averaged

LLPAs built in

Credit, LTV, occupancy, and property adjustments already priced — so the number holds up when you quote it.

Deployed on listings nationwide

By originators at independent mortgage banks, depositories, and credit unions — with their agent and builder partners.
1,800+

Originators

3

Pricing engines

What it does

A payment that’s right the moment it’s read

A rate printed on a mortgage listing flyer is wrong within a day, so the payment figure becomes decoration. Homebuyers know it, agents know it, and the one question that matters goes unanswered while someone is standing in the house.

For the buyer

The number they came for, without the need to be there

Homebuyers look at listings on a weekend and at open houses you aren’t attending. The flyer answers while you’re somewhere else, using your live pricing rather than an outdated generic estimate.

  • Real payment scenarios using your actual pricing
  • Down payment assistance, seller credits, and temporary buydowns
  • Loan-level price adjustments applied
For you

Something agents want that costs them nothing

Every originator in the market is asking the same agents for the same referrals. Almost none of them arrive with something that makes the listing itself perform better.

  • Share a financing flyer with an agent partner in a couple of clicks
  • Your name and pricing on it, wherever the flyer travels
  • Nothing for the agent to build, buy, or learn
What the buyer sees

Your pricing, on their screen, at the listing

Ranked loan options with the total payment and rate. Taxes and insurance included, so the number is the number rather than a principal-and-interest tease.

  • Conventional and FHA scenarios side by side, ranked by payment
  • Full breakdown available — points, P&I, taxes, insurance, HOA
  • Adjustments already priced in, so nothing changes when you run it yourself
  • Disclosures and assumptions carried on the page
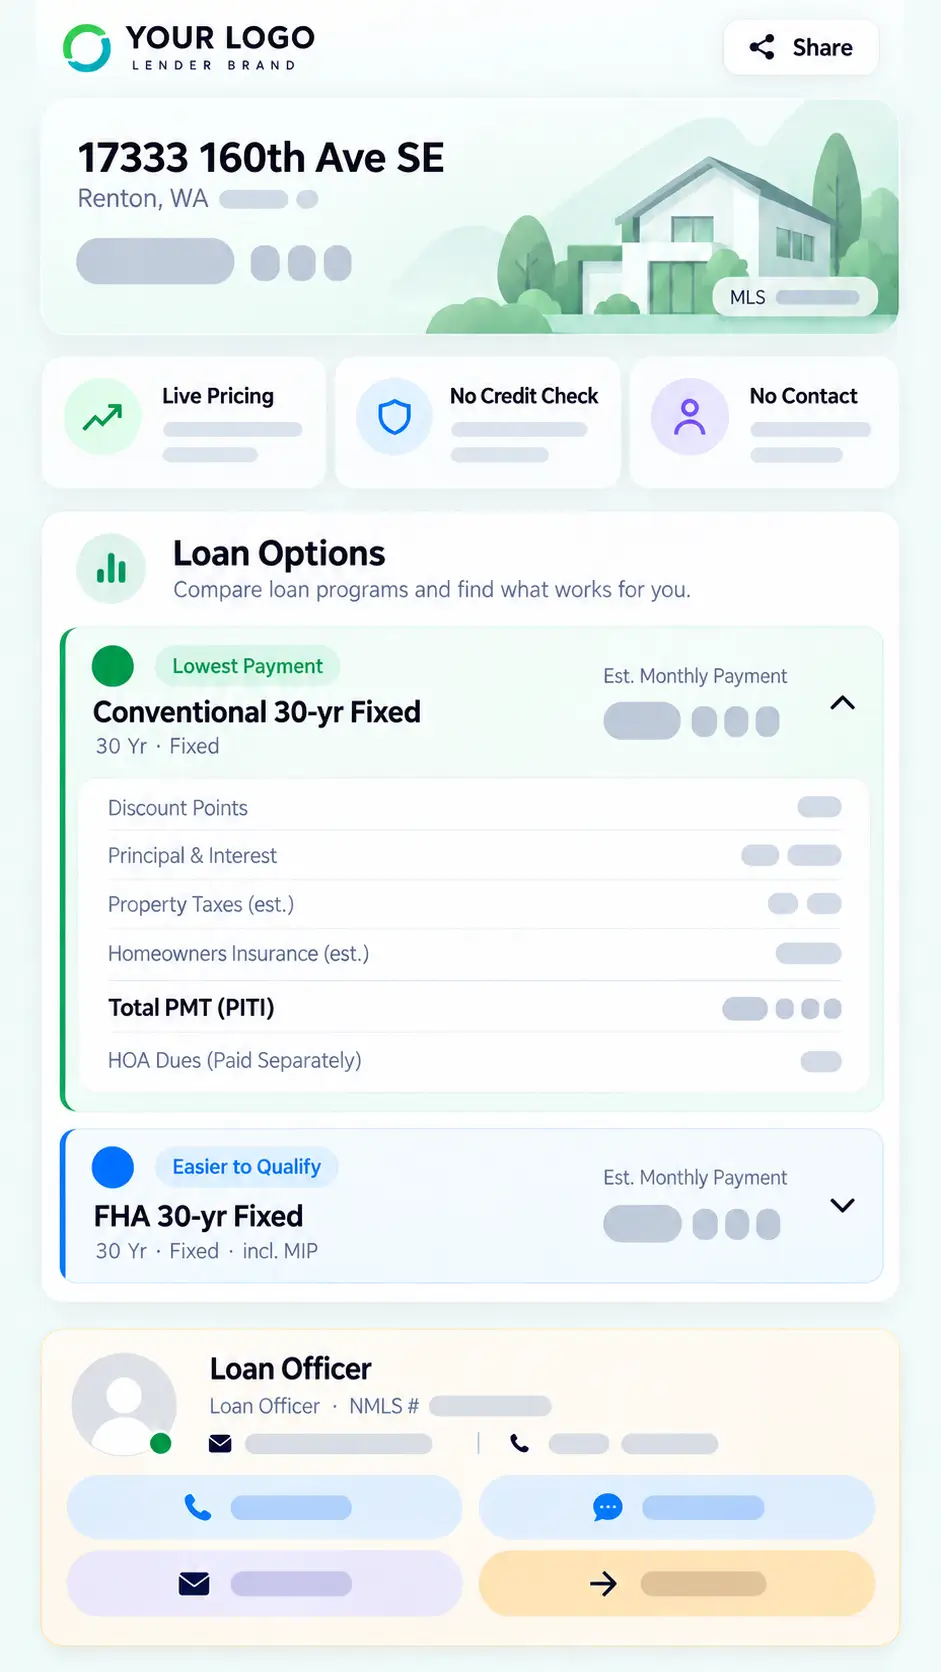
Loan options page showing a property summary, conventional and FHA mortgage options with estimated monthly payments, and loan officer contact information.
Actual Product — Rates and payments obscured for this page
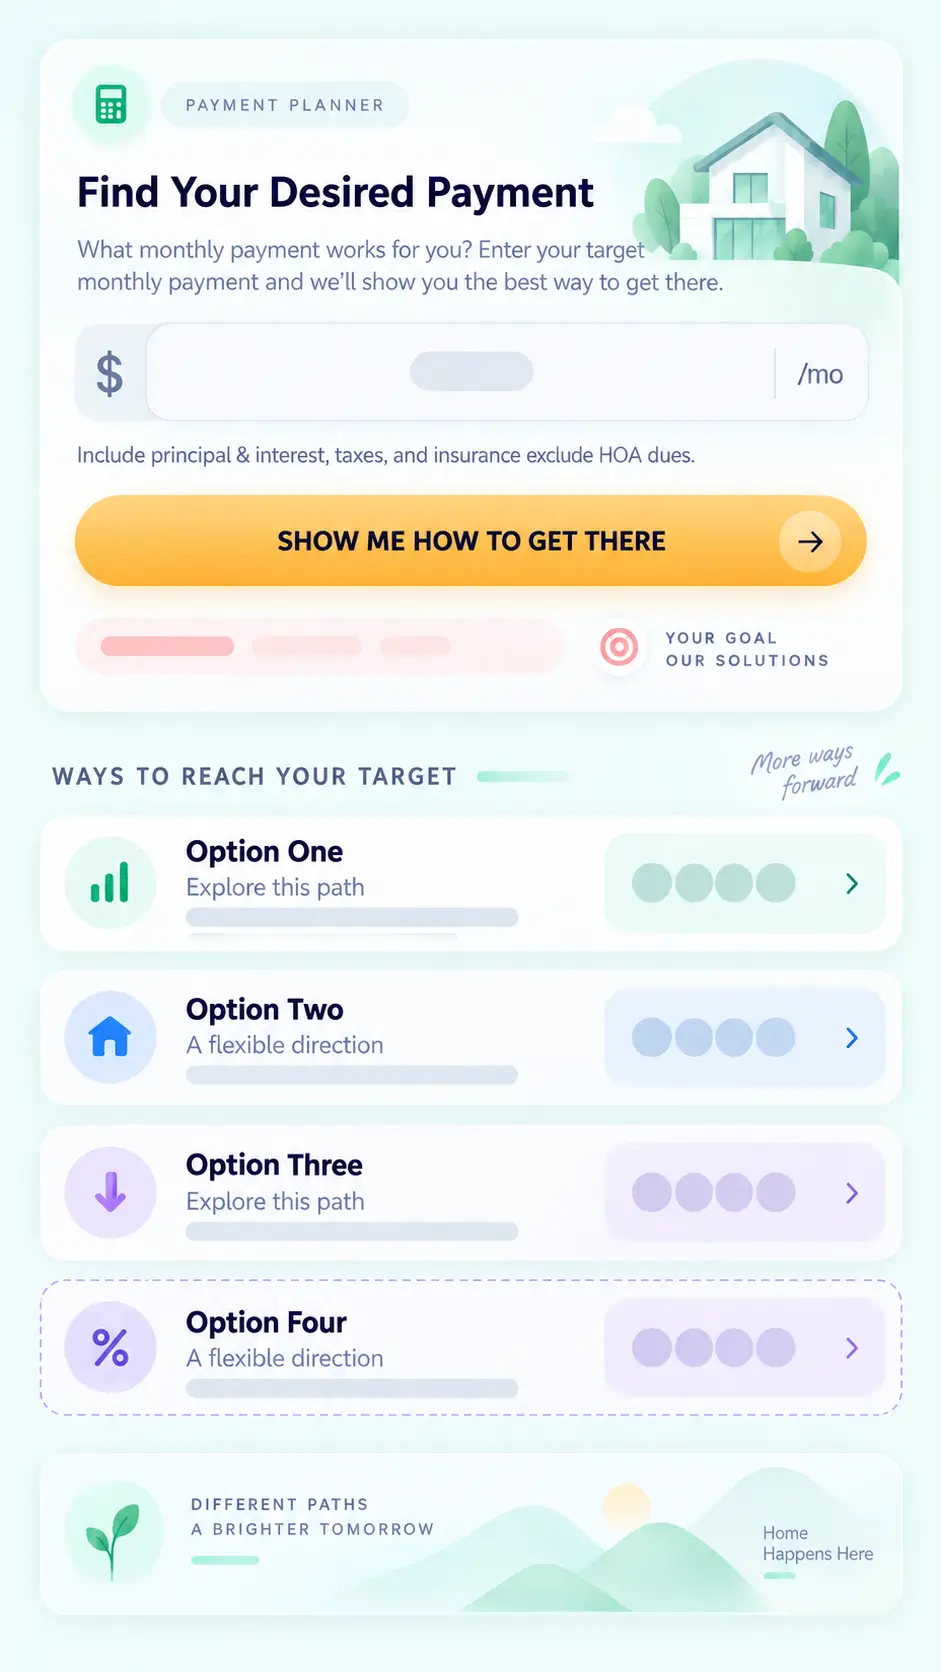
Payment planner showing a target monthly mortgage payment and ways to reach it, including a rate buydown, lower home price, higher down payment, and temporary buydown.
Actual Product — Rates and payments obscured
The part agents remember

Homebuyers shop by payment, not by price

The real estate listing advertises a price. The buyer standing in front of it is doing math on a monthly number. Let them enter that number and see several ways to reach it.

  • Each route determined with your pricing, adjustments included
  • Turns “we can’t afford it” into a structured conversation
  • Gives the agent something to take back to the seller

This is the feature agents tell other agents about, and it is why the second listing is easier to get than the first.

Getting it out there

Two ways in, both of them one step

Most originators share the mortgage listing flyer directly. Some agents would rather keep their own marketing and add a QR code to it. Either works, and neither asks the agent to learn anything.

Most common

Share the financing flyer

You generate a financing flyer for the property and send it to your agent partner. They pass it to buyers, post it, or leave it at the open house. Your pricing, your name, live wherever it lands.

When the agent has their own materials

Hand over a QR code

The agent adds your code to marketing they already produce. A QR code carries no rate and no payment, so their flyer stays a plain real-estate flyer with nothing that needs updating.

Pricing

Priced to fit how you actually operate.

Tell us your size and structure and you’ll have a real number, usually on the first call.

Who this shows up for

The same tool, three different reasons to want it

Loan officers

Win agent business

Arrive with something that makes the listing perform, instead of asking for referrals empty-handed.

Real estate agents

Listings that answer

Homebuyers get real numbers at your real estate listing, so fewer of them stall on affordability.

Builders

Fewer concessions

Buyers at the model home see what a payment actually looks like, including assistance options your lender offers.

Questions

Before you start

A mortgage listing flyer is financing collateral tied to a specific property, showing what a buyer’s monthly payment would be. Uplist flyers price from the originator’s own live pricing rather than a printed rate, so the payment is current whenever the buyer reads it.

No. Buyers see live payment options with no credit pull, no Social Security number, and no contact form. They explore anonymously and reach out when they choose to.

Pricing is based on the products you choose and your team size. Talk to our team for a quote tailored to your organization.

No. Uplist flyers carry financing information only. They do not promote the property and they carry no agent branding, which is the distinction that separates a financing tool from co-marketing. The structure has been reviewed by counsel.

No. The originator shares a financing flyer with the agent, or provides a code the agent can add to marketing they already produce. There is nothing for the agent to build, buy, or learn, and nothing about it changes their own obligations.

Yes, and most prefer it. The loan officer provides a code the agent places on marketing they already produce. The code carries no rate and no payment, so the agent’s flyer stays a plain real-estate flyer.

From each customer’s own pricing engine. Uplist connects to Optimal Blue, Polly, and LoanSifter, so payment scenarios reflect what that lender would actually offer, with loan-level price adjustments applied.

Next step

Put a brain on your next listing

Evaluating for a company?

Uplist is a technology provider. Uplist is not a lender or mortgage broker, does not originate loans, and does not make credit decisions. Any payment or rate figures shown through Uplist products are estimates provided by the originating lender, are subject to change, and are not a commitment to lend or a guarantee of approval or of rate availability. Pricing shown on this page is subject to change. Equal Housing Opportunity.

Go to Top